Show notes
On this page
On this page
Your students are training for a career that moves in cycles. The good years are very good. But every 8 to 10 years, a big ripple hits the airline industry. The students who are ready for it keep flying. The ones who aren’t panic.
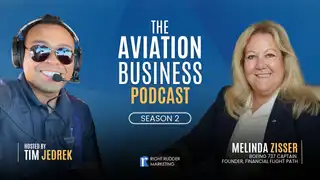
In this episode of The Aviation Business Podcast, host Tim Jedrek talks with Captain Melinda Zisser, a retired airline pilot, former Boeing 737 line check pilot, and founder of Financial Flight Path. She explains why flight schools feel the industry’s turbulence first, what your students need to know before they sign a training loan, and how a simple checklist can protect your money and your flight school’s.
Episode highlights
Flight schools feel the turbulence first
Major airlines have cash and investors to lean on. Most flight schools don’t. When the economy dips or fuel prices climb, your bottom line takes the hit first.
Tim pointed to the fuel spike earlier this year, when some schools saw their fuel prices nearly double overnight. Melinda called it a barrier to entry for anyone who wants to fly. And without flight schools, she said, the airlines have no pipeline of quality students.
The 8-to-10-year cycle, lived
Melinda’s career reads like a map of the industry’s downturns. Two of her early airlines closed their doors. She landed at a major airline in February 2001, and 9/11 grounded her a few months later.
She chose not to flow back to an express carrier. Instead, she built a real estate business to support her family. When she returned to flying in 2005, she kept that side business, and she still runs it with a partner more than 20 years later. That second income carried her through being displaced in 2008 and through COVID.
Her message for your students: right now is a good year. But the dips come, and they need to be ready before they do.
A flight plan for your money
Even if you stay in the pattern, you have a flight plan. You know how long you’ll fly, how much reserve you need, and how much fuel to carry before you take off. Melinda found that most people, pilots included, have no plan like that for their money.
So she built one. Financial Flight Path is a seven-week course with six modules and a “turbulence” lesson in the middle: what to do when something interrupts your pattern, like a new baby, a death in the family, or four new tires.
The same thinking works for your flight school. A five-year plan answers a hard question: can your numbers survive a 25% drop in revenue? When you know the answer, you can make bolder moves with confidence.
Money rules, and why one fleet type wins
Melinda keeps personal “money rules,” the same way some people keep food rules. One of hers: don’t invest in anything you don’t understand.
Your flight school can have money rules too. Maybe yours is “Cessnas only.” Tim agreed that schools sticking to one make and model usually keep maintenance costs lower. Parts are easier to stock, and mechanics know the airplane by heart. The multi you need for MEI and multi-engine add-ons is the exception.
Training loans: know the price and the payback day
Melinda isn’t against training loans. She called them pretty much the only way to accelerate flight training today. But your students need to know what they’re signing, what the loan really costs, and when they can expect a return.
Too many students think a $100,000 loan leads straight to a major airline. It leads to a regional first. Melinda said a regional first officer can bank on around $65,000 a year, before the taxes and deductions come out. Paying a loan and rent on that pay often means renting a room, not an apartment.
Tim started training around 2020 and remembers being told the airline job would solve everything. His advice: the best time to start is yesterday, and then you prepare for the next cycle. By the time a student finishes training, the market will look different.
What a new first officer should do first
Using a new regional first officer as the example, Melinda laid out the order:
- Learn the job first. Spend the first six to eight months on the airplane, the company manual, and the culture.
- Read your first paycheck. Federal tax, state tax, Social Security, Medicare. The deductions add up fast.
- Save automatically. Put 10% or 15% into a 401(k) or Roth, or whatever you can. The habit matters more than the amount.
- Know your burn rate. Tim’s term for your monthly cost of living. Live below it.
- Learn to invest in year two. Once the job is under control, start learning where your money goes.
Every one of these habits can start while your students are still in training.
Fiduciary vs. broker
After she came back to flying in 2005, Melinda worked with a broker who managed her 401(k). She didn’t really understand what she owned or what she paid in fees. A broker, she explained, makes money each time they trade. A fiduciary works in your best interest for a fee that should be in writing, with regular reporting.
She met her fiduciary in 2012 and now meets with him every quarter. Her rule: interview at least three flight schools, and interview at least three fiduciaries.
The best question an advisor ever asked her wasn’t “What do you have?” It was “What do you want your money to do?” Flying from LA to New York takes more fuel than LA to Vegas. Your money works the same way.
Pay yourself first
For pilots, that means the 401(k) or Roth comes out before anything else. For flight school owners, Tim shared what changed his own business: the book Profit First. Set aside a percentage of revenue for profit, owner pay, and taxes before you pay operating expenses. Start small, even $100, and build the muscle.
Melinda added that many small business owners don’t have a grip on their numbers. She was clear that she isn’t a financial planner, and she encouraged owners to talk with their planner and accountant about retirement accounts and business structures that fit their flight school.
Know your numbers before they become problems
A few years ago, Melinda got a $300 water bill. Her normal bill ran $90 to $120. Because she knew her numbers, she called a plumber right away and found a sprinkler leak. Waiting two more months would have cost her about $1,000.
Your flight school works the same way. Track revenue and fuel burn per airplane and per student, and you’ll spot problems early. Tim walks his flight school partners through hours flown per tail number each month, leads per month, cost per lead, and customer acquisition cost compared with the lifetime value of a student.
Her reading list
Melinda reads widely and suggests you notice who each author is writing for. Two favorites came up: Rich Dad Poor Dad by Robert Kiyosaki and Secrets of the Millionaire Mind by T. Harv Eker. Eker’s book turned out to be Tim’s favorite too. Melinda also wrote a blog post for pilots called Rich Pilot, Poor Pilot.
Notable quotes
“The flight schools actually are probably more prone to the turbulence of the industry.”
Melinda Zisser
“Even if I’m staying in the pattern, I have a flight plan. And what I found is that most people, not just pilots, don’t have a plan for their money.”
Melinda Zisser
“I’m not telling you not to take out the loans. But I do believe that you need to be educated on that price of the loan.”
Melinda Zisser
“Interview at least three flight schools, interview at least three fiduciaries.”
Melinda Zisser
“When you know your numbers, you can see where there’s an issue well before it becomes critical.”
Melinda Zisser
“The best time to start is yesterday, and then you have to prepare for the next cycle.”
Tim Jedrek
About Captain Melinda Zisser
Melinda Zisser is the founder of Financial Flight Path, a financial education course built for pilots. She flew for more than 30 years as a Part 121 airline pilot and recently retired after reaching the federal age limit for airline pilots. Her last position was line check pilot on the Boeing 737, where she trained and checked other pilots.
Before her airline career, Melinda was news editor of the South Florida Business Journal and worked as a flight instructor on the side. She trained under a former Eastern Airlines line check pilot who opened his own flight school. She has also run a real estate business with a partner for more than 20 years, which kept her finances steady through 9/11, the 2008 recession, and COVID. She lives in Florida.
Connect with Melinda
- Financial Flight Path: financialflightpath.com. Join the waitlist to get her fiduciary guide and top ten checklist. Her seven-week course starts November 22.
- Social: Financial Flight Path on Facebook, Instagram, and LinkedIn
- LinkedIn: linkedin.com/in/mzisser
This episode is financial education, not individual financial advice. Melinda speaks for herself, not for any airline.
Grow your flight school with Right Rudder Marketing
Talking about numbers like cost per lead and student lifetime value is what we do every day with flight schools across the country. If you want help filling your pipeline with students, talk to our team.
Let’s train more pilots.